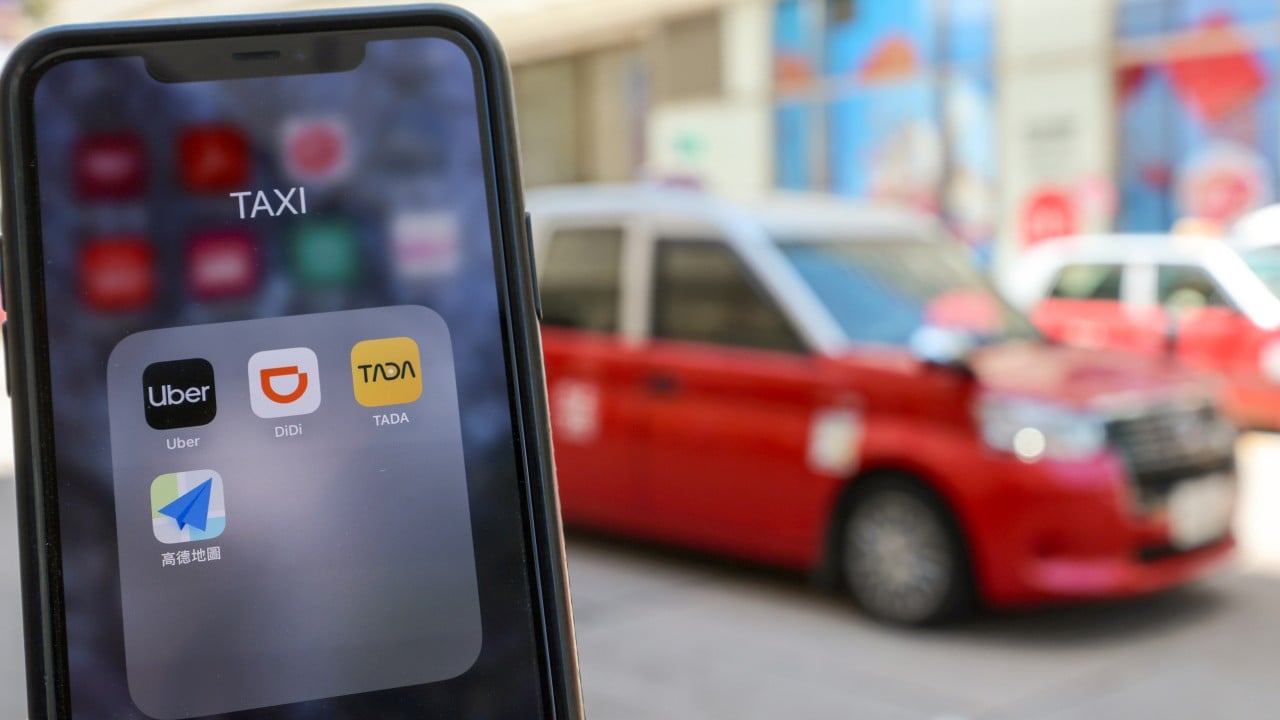
Eight companies have formally submitted applications for Hong Kong ride-hailing licences ahead of the government’s regulatory deadline, marking the end of more than a decade of legal ambiguity for point-to-point transport in the city. While official channels frame this milestone as a victory for commuter choice and smart city modernization, the underlying math tells a far more restrictive story. The new licensing framework does not liberate the market. Instead, it institutionalizes a strict supply cap, forces platforms into capital-heavy fleet ownership or rigid taxi partnerships, and ensures that Hong Kong ride-hailing licences remain an expensive, tightly rationed commodity rather than an open marketplace.
For over ten years, the street-level reality in Kowloon and on Hong Kong Island contradicted the law on the books. Commuters tapped screens to summon private cars while lawmakers debated definitions of hire-car permits, insurance liabilities, and taxi medallion values. Now, the deadline has passed, and eight contenders have stepped forward to claim a piece of a newly legalized, heavily policed pie.
The Anatomy of a Controlled Market
To understand why eight applicants rushed to file paperwork before the cutoff, you first have to look at what the Transport and Logistics Bureau actually put on the table. Unlike the early expansion models used in London, Singapore, or San Francisco—where platforms acted as pure software intermediaries connecting anyone with a valid driver’s licence and a sedan to a paying passenger—Hong Kong engineered a closed-loop system.
The government’s regulatory architecture separates the ecosystem into two distinct tiers. First, the platform licence, which governs the digital dispatch network, pricing algorithms, safety protocols, and customer dispute resolution. Second, the vehicle and driver permits, which remain tethered to strict quotas and commercial insurance mandates.
This distinction is everything. A platform can win a licence to operate an app, yet still face an acute shortage of legal vehicles to dispatch.
Consider how traditional ride-hailing scales. In an open market, surge pricing draws part-time drivers onto the road during a rainstorm in Central or after a concert at Kai Tak. Supply expands and contracts dynamically. Under Hong Kong’s newly formalized rules, part-time gig driving with a standard private car remains largely locked out unless that specific vehicle holds a commercial hire-car permit. Because those permits are capped and expensive, platforms cannot rely on an elastic army of casual weekend drivers. They must compete aggressively for a finite pool of licensed commercial vehicles and existing red, green, and blue taxis.
Who Shows Up When the Rules Favor Incumbents
While the Transport Department keeps the full roster of commercial applicants confidential during the vetting phase, the structural profile of the eight contenders is unmistakable to anyone who has tracked Asian mobility markets over the past decade. The barrier to entry—measured in statutory deposits, local server compliance, 24-hour customer service centers, and mandatory fleet commitments—eliminates small startups immediately.
The applicant pool breaks down into three distinct strategic camps.
The Global and Regional Tech Giants
Established cross-border platforms have treated Hong Kong as a prestige market for years, operating in the gray zone while absorbing legal fees and driver fines as the cost of customer acquisition. For these operators, applying for a formal licence is defensive survival. Losing access to Hong Kong means surrendering high-margin airport transfers and corporate accounts to rivals. These companies bring unmatched routing algorithms, deep cash reserves, and massive user bases already installed on millions of smartphones. Their weakness is compliance friction; translating global gig-economy software into a rigid, quota-bound local dispatch system requires expensive engineering overhauls.
The Mainland Mobility Powerhouses
Cross-border integration between Hong Kong and the Greater Bay Area has reshaped transport priorities. Major mainland ride-hailing platforms, backed by vast capital and experience operating under strict municipal quotas in cities like Shenzhen and Guangzhou, view Hong Kong as a natural southern extension of their networks. They already understand how to manage state-mandated vehicle caps, electric vehicle fleet transitions, and dual-licence cross-border vehicles. Their entry introduces fierce price competition, though they face local consumer skepticism regarding data privacy and familiarity with Hong Kong’s labyrinthine one-way street grids.
The Local Taxi Consortiums and Fleet Operators
Perhaps the most consequential applicants are the domestic conglomerates and newly formed taxi fleet syndicates. Having spent years lobbying against unlicensed private cars, major medallion owners and transport operators realized that obstruction alone could not stop digital dispatch. By forming corporate fleets—often backed by government-encouraged taxi fleet licensing schemes—these traditional players are attempting to become platform operators themselves. They possess the one asset tech giants cannot easily manufacture: thousands of already-licensed vehicles and veteran drivers who know every back alley from Kennedy Town to Kwun Tong.
The Medallion Hangover
You cannot analyze Hong Kong ride-hailing licences without confronting the elephant in the room: the taxi licence medallion.
For decades, Hong Kong’s 18,163 taxi licences functioned less like transport permits and more like high-yield commercial real estate. Because the government froze the issuance of new taxi licences in the 1990s, existing medallions traded on an open secondary market, peaking at over HK$7 million each in 2015. Banks issued mortgages against them. Retirees treated them as pension funds. Fleet syndicates leveraged them to build family fortunes.
Then came smartphones, declining service standards, and refusal-of-hire complaints that alienated an entire generation of riders. Medallion values tumbled, shedding more than half their peak value as investors priced in the inevitable legalization of ride-hailing.
Every policy decision surrounding the new licensing regime is a balancing act designed to prevent a total collapse of those remaining medallion values, which could trigger defaults across local commercial lenders. By capping the number of non-taxi hire-car permits and encouraging ride-hailing platforms to onboard existing taxis, regulators crafted a soft landing for entrenched owners.
It is a classic Hong Kong compromise. Commuters get a legal app to press. Medallion holders get a protected moat around vehicle supply. And the eight applicants are left fighting over the razor-thin margins in between.
The Unit Economics Trap
Winning one of these licences is only the opening bell. Making money under the new rules is a completely different fight.
In a hypothetical example of how platform economics work under supply caps, imagine a newly licensed operator trying to guarantee a four-minute pickup time in Tsim Sha Tsui during the evening rush. Because the total number of licensed vehicles in the city is fixed, the platform cannot simply onboard five thousand new part-time drivers next month. Instead, it must poach existing licensed drivers from the other seven applicants.
How do you poach a driver in a supply-constrained market? You cut your commission rate or pay cash bonuses.
When eight platforms chase the same limited pool of drivers, driver acquisition costs skyrocket while platform take-rates plummet. If a platform normally takes a 20 percent cut of a HK$150 fare, competitive pressure in a capped market quickly forces that commission down toward 10 percent—or even zero during promotional wars. Simultaneously, platforms face massive fixed compliance costs:
- Commercial Insurance Mandates: Private car policies do not cover fare-paying passengers. Commercial hire-car insurance in Hong Kong carries steep premiums, particularly for vehicles operating in dense urban corridors with high minor-collision rates.
- Fleet Maintenance and Electrification Targets: Regulators increasingly tie permit approvals to zero-emission vehicle quotas, forcing operators or their fleet partners to absorb higher upfront capital costs for electric sedans and vans.
- Statutory Penalties and Auditing: Under the new framework, platforms face direct corporate liability if an unlicensed vehicle slips onto their dispatch network, requiring continuous real-time verification of driver IDs, vehicle registration marks, and insurance validity.
The result is a structural squeeze. Platforms face high fixed regulatory overhead on one side and capped supply on the other. History shows that when eight competitors enter a capped mobility market, at least half of them bleed cash for twenty-four months before consolidating, merging, or quietly handing back their keys.
What Happens to the Commuter
Lost in the corporate maneuvering and legislative fine print is the person standing on the curb in the rain in Wan Chai.
For the everyday passenger, the immediate aftermath of the licensing deadline will feel remarkably familiar—and potentially more expensive. During the unregulated era, riders benefited from venture-capital subsidies and an informal supply of part-time drivers willing to work peak hours for extra cash. As enforcement tightens against unlicensed drivers who fail to secure permits under the new regime, the total number of cars available on the road during Friday nights or typhoon warnings may actually shrink in the short term.
Legality brings accountability. Passengers will finally have clear insurance coverage in the event of a collision, standardized complaint mechanisms, and transparent digital receipts. Nobody has to pretend they are "riding with a friend" if a traffic officer flags down the car near the Cross-Harbour Tunnel.
Yet legality also brings friction. Dynamic surge pricing, while regulated against extreme price gouging, will hit the ceiling faster when supply cannot expand to meet demand. Platforms will prioritize higher-tier, luxury-class vehicles—where profit margins survive the heavy cost of commercial permits—leaving budget-conscious riders waiting longer or defaulting back to street-hailing red taxis.
The Regulatory Blind Spot
The biggest vulnerability in the new licensing framework lies in cross-border enforcement and driver credentialing.
As Hong Kong integrates deeper into the Pearl River Delta transport grid, the distinction between local point-to-point transport and cross-border private hire becomes increasingly blurry. Furthermore, driver demographics present an acute bottleneck. Hong Kong’s professional driving workforce is aging rapidly, with a large percentage of commercial licence holders over the age of fifty-five. Younger workers rarely view full-time driving as a viable career given the cost of living and high vehicle rental fees.
Issuing licences to eight tech companies does not create a single new driver. Unless the government reforms commercial driving test waitlists—which routinely stretch for months—or loosens rules allowing vetted, part-time drivers to operate under umbrella platform insurance policies, all eight platforms will end up fighting over the exact same aging pool of full-time operators.
Consolidation Is Baked Into the Math
Hong Kong’s transport history leaves zero doubt about how an eight-player race ends. Look at the city’s telecommunications sector, its supermarket duopoly, or its franchised bus networks. High fixed costs, scarce physical infrastructure, and strict regulatory oversight inevitably punish fragmentation and reward scale.
Right now, eight applicants are celebrating their entry into a newly legitimized market, projecting growth charts to boards and regulators. Within three years, the capital burn of subsidizing fares while paying premiums for a capped supply of licensed cars will separate the balance sheets that can endure from those that cannot. The real battle is no longer about winning a piece of paper from the Transport Department; it is about surviving the brutal, low-margin attrition war required to buy out the losers.